When an insurer pays less than the cost to restore a Texas business property, the difference may appear as a depreciation holdback or a disputed actual cash value calculation. A commercial property claim depreciation dispute for Texas property owners requires more than comparing one check with one contractor estimate. The policy, the damaged property, the carrier’s valuation method, and the steps required to recover withheld amounts all matter.
For a business owner, the issue can affect repairs, financing, tenants, inventory, and whether the property can operate normally. This guide explains how depreciation can affect a commercial claim, what to preserve, and when a payment should receive a closer legal review. It is general information, not a legal opinion about any particular policy or loss.
Call Hoch Law Firm at 817-731-9703 to discuss a Texas commercial property claim.
What depreciation means in a commercial property claim
Depreciation is an adjustment for age, wear, condition, or obsolescence. In a basic actual cash value calculation, the insurer starts with an estimated replacement cost and subtracts an amount attributed to depreciation. The result is intended to reflect the property’s value at the time of the covered loss, but the policy controls how the carrier should calculate and pay the claim.
The Texas Department of Insurance commercial property insurance guide distinguishes replacement cost coverage from actual cash value coverage. Replacement cost coverage generally addresses the current cost to repair or replace covered property, while actual cash value coverage accounts for depreciation. A commercial policy may use one method for some property and another method for a different coverage or component.
That means an insurer’s use of the word depreciation does not answer every question. A careful review asks:
- What coverage applies to the damaged building, roof, equipment, fixtures, inventory, or other property?
- Does the policy provide replacement cost, actual cash value, or a combination?
- What does the policy say about when withheld depreciation becomes payable?
- Does the estimate identify the item being depreciated and explain the calculation?
- Does the amount match the condition and remaining useful life of the specific property?
Why a commercial claim may have a depreciation dispute
A disagreement can arise before the carrier issues its first payment, after the initial actual cash value payment, or when the policyholder requests the remaining replacement cost benefits. The dispute is often about the application of the policy rather than the existence of damage alone.
The carrier’s estimate does not explain the holdback
An estimate may show a line-item deduction without stating why that percentage applies to the damaged component. A property owner may need the underlying scope, age assumptions, condition evidence, and pricing information to evaluate whether the deduction is supported.
The same percentage is applied to different components
A roof system, flooring, mechanical equipment, and interior finishes do not necessarily have the same age, condition, service life, or replacement characteristics. A blanket depreciation percentage can raise questions when the estimate does not distinguish among the items.
The carrier treats replacement cost benefits as permanently unavailable
Some replacement cost provisions initially pay actual cash value and hold back part of the estimated replacement cost until repairs or replacement are completed. The policy may impose notice, repair, documentation, or timing requirements. A property owner should not assume the holdback is lost, and should not assume it is automatically owed without checking the policy conditions.
The scope or price is disputed as well
Depreciation may be only one part of the shortfall. The parties may also disagree about the cause of damage, the quantity of work, matching materials, code-related work, overhead and profit, business personal property, or the cost to complete repairs. Separating each issue makes the claim easier to evaluate.
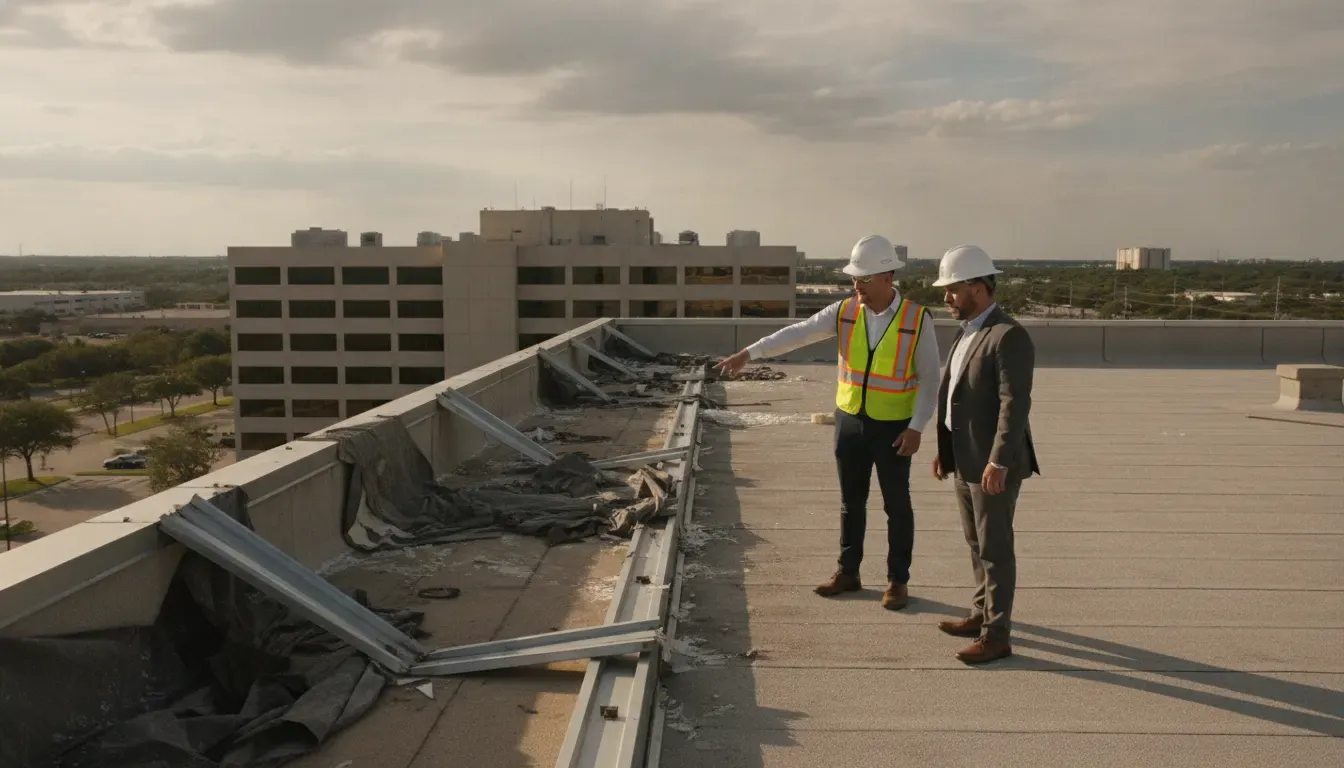
How to review a disputed depreciation calculation
A business owner can organize the claim before asking counsel to assess the dispute. The goal is not to create a new estimate without support. It is to identify what the carrier calculated, what the policy requires, and what evidence supports a different result.
- Collect the complete policy. Save the declarations, endorsements, forms, conditions, exclusions, loss settlement provisions, and any coverage-specific schedules. A certificate or summary page is not a substitute for the full policy.
- Separate the estimates. Keep the carrier’s estimate, contractor bids, engineer or consultant reports, invoices, photographs, and proof of payment in a dated file. Mark changes rather than overwriting earlier documents.
- Identify each holdback. Create a simple line-item list showing the damaged component, replacement-cost amount, depreciation amount, actual cash value payment, deductible, and any unpaid balance. Ask the carrier to explain unclear entries in writing.
- Check the repair condition. Review the policy language and correspondence about completing repairs, selecting contractors, submitting invoices, and requesting withheld amounts. Do not sign a release or close the claim before understanding what rights it affects.
- Preserve the property’s condition evidence. Keep photographs, videos, maintenance records, prior inspections, leases, inventory records, and communications with adjusters and vendors. Do not discard damaged materials when preservation is reasonably possible and safe.
These steps do not determine whether a carrier breached a policy. They create a reliable record for comparing the claimed damage, the valuation method, the policy terms, and the amount paid.
What Texas property owners should preserve after an underpayment
Commercial claims often involve multiple people and moving deadlines. Preserve original emails, claim numbers, adjuster communications, recorded statements, inspection notices, estimates, photographs, invoices, repair contracts, and proof of lost business income when applicable.
Keep a chronology that records the loss date, notice to the insurer, inspections, requests for information, payments, supplemental submissions, and responses. If a carrier says information is missing, preserve the request and the material supplied in response. A clear chronology can reveal whether the disagreement concerns coverage, scope, depreciation, proof of loss, timing, or several issues at once.
Protect safety first. Emergency mitigation and necessary temporary repairs may be appropriate, but document the condition before work begins whenever possible. Ask contractors to distinguish emergency work, permanent repairs, upgrades, and code-required work. Those categories may be treated differently under the policy and Texas law.
Can an insurer depreciate every part of a commercial property claim?
There is no universal answer that applies to every Texas commercial policy. The policy language, coverage form, damaged property, valuation provision, and facts of the loss control. A carrier should be able to identify the basis for a deduction instead of treating a generalized percentage as self-proving.
Texas Department of Insurance Bulletin B-0045-98 addresses calculation of actual cash value under the Texas Standard Homeowner’s Policy Form B. The bulletin states the Department’s position that certain contractor overhead, profit, and sales-tax deductions were improper under that residential policy language. It does not replace the analysis of a commercial policy, but it illustrates why the exact policy wording and valuation method matter. Property owners should avoid treating a residential bulletin as an automatic answer to a commercial dispute.
Texas appellate decisions also show why commercial property disputes turn on policy wording and proof. In Triyar Companies v. Fireman’s Fund Insurance Co., the court discussed replacement cost, actual cash value, depreciation, repair or replacement conditions, and the evidence needed to support a recovery under the policy at issue. A case involving different language or facts may produce a different result.
What should a property owner do after receiving a low payment?
Start by preserving the payment explanation and asking for the carrier’s complete estimate and valuation basis. Compare the line items with the policy and with documented repair needs. Avoid making a final statement that the payment resolves the claim until the release, policy conditions, and remaining coverage are understood.
Next, consider whether an independent adjuster, contractor, engineer, accountant, or other qualified professional is needed to clarify the loss. The right professional depends on the disputed issue. A roof-scope disagreement, business-income claim, and valuation dispute may require different evidence.
Finally, obtain legal guidance promptly when the carrier denies coverage, refuses to explain the depreciation, disputes the repair scope, delays a decision, demands a release, or treats a supplemental request as closed without a clear policy basis. Texas insurance claims can involve deadlines and notice requirements, and delay can make evidence harder to preserve.
Call 817-731-9703 to discuss a disputed commercial property insurance payment with Hoch Law Firm.
How a Texas commercial property claim attorney can help
A property insurance attorney can review the policy, claim file, estimates, payment history, and supporting evidence together. The attorney may help identify whether the central issue is depreciation, scope, coverage, causation, a policy condition, business interruption, or a combination of disputes.
Hoch Law Firm represents policyholders in commercial property insurance disputes involving business properties such as office buildings, retail centers, warehouses, manufacturing facilities, apartment complexes, and other commercial operations. The firm does not represent insurance companies. Its commercial property insurance page describes the types of property and coverage disputes the firm handles.
For broader information about policyholder representation, see Hoch’s Fort Worth property insurance lawyer page. For a general explanation of the depreciation concept, review the firm’s commercial property insurance depreciation guide. That guide is the broader depreciation resource; this article focuses on the post-loss dispute, documentation, and claim-review decisions that may follow an underpayment.
Call Hoch Law Firm at 817-731-9703 for a free case evaluation of a Texas property insurance dispute.
Frequently Asked Questions
What is a depreciation holdback on a commercial property claim?
A depreciation holdback is an amount not included in an initial payment because the carrier applied an actual cash value calculation or a replacement-cost condition. Whether the amount is recoverable depends on the policy, the damaged property, repair documentation, and applicable claim requirements.
Does replacement cost coverage always pay the withheld depreciation?
Not automatically. A policy may require repairs, replacement, notice, invoices, or other proof before releasing withheld amounts. Review the loss settlement language and claim correspondence instead of relying on a general rule.
Can a Texas insurer use one depreciation percentage for the whole building?
A single percentage may raise questions when different components have different ages, conditions, or useful lives, but the policy and evidence control. Ask the carrier to identify the basis for each disputed deduction.
Should a business owner sign a claim release after receiving the first payment?
Do not sign a release without understanding whether it ends the claim or waives additional benefits. Have the release, payment explanation, and policy reviewed when the amount or scope of the claim remains disputed.
How long does a Texas commercial property claim dispute take?
Timing depends on the policy, investigation, damage scope, evidence, negotiations, and whether litigation is necessary. A prompt review can help preserve evidence and identify policy deadlines, but no timeline can be promised without evaluating the claim.
Call 817-731-9703 to learn whether Hoch Law Firm can help with your commercial property claim.