Fire Damage Insurance Claim Lawyer for Texas Businesses
A commercial fire can stop revenue overnight while repair bills, payroll, loan payments, and customer obligations continue. The insurer may promptly open a file, but that does not guarantee it will recognize the full loss or pay it on time. A fire damage insurance claim lawyer can protect a Texas business from an incomplete investigation, an undervalued estimate, or an unsupported denial while the owner focuses on preserving operations and rebuilding.
Call Hoch Law Firm at 817-731-9703 for a free case evaluation of your Texas commercial fire claim.
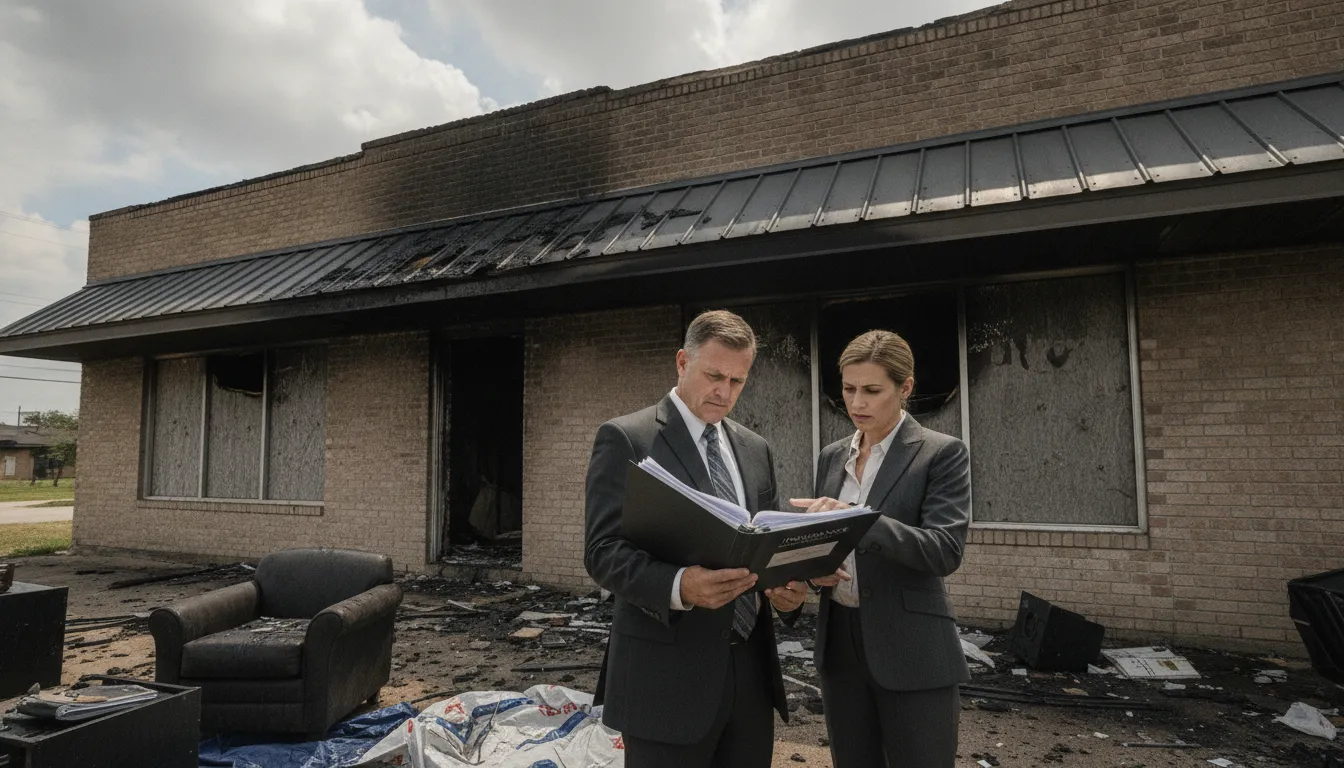
A commercial fire claim is rarely limited to visible burn damage. Smoke can contaminate inventory and mechanical systems. Fire suppression water can damage portions of the property that flames never reached. Debris removal, code-required upgrades, temporary space, equipment replacement, and lost income may create separate coverage questions. Each category requires proof, and each may be subject to different limits, deductibles, exclusions, and deadlines.
Hoch Law Firm exclusively represents policyholders and injured parties, not insurance companies. The firm provides personalized legal service and direct attorney access for business owners facing serious claim disputes. Tim Hoch is Board Certified in Personal Injury Trial Law and brings trial-focused judgment to complex matters in which the insurer disputes the cause, scope, or value of a loss. Representation is available on a contingent-fee basis, and the firm offers a free case evaluation.
What a Texas Commercial Fire Claim May Include
The policy controls what the insurer owes. Business owners should obtain a complete certified copy, including declarations, endorsements, schedules, exclusions, and forms incorporated by reference. A coverage analysis should identify every potentially applicable part of the policy rather than treating the incident as a single building-damage claim.
Depending on the language and facts, a commercial fire claim may include the following losses:
- Building damage: Repairs or replacement involving the roof, walls, floors, electrical system, plumbing, fire protection systems, and structural components.
- Business personal property: Inventory, furniture, machinery, computers, records, fixtures, raw materials, and finished goods.
- Smoke and soot contamination: Evaluation and remediation of porous materials, HVAC systems, electronics, products, and interior finishes.
- Water and chemical damage: Loss caused by sprinklers, hoses, suppression chemicals, and moisture migration after the fire.
- Debris removal and professional expenses: Covered costs associated with clearing the site, assessing damage, and preparing the claim.
- Ordinance or law costs: Additional expense required to rebuild in compliance with current codes when the policy provides that coverage.
- Business income and extra expense: Covered income loss and reasonable additional costs during the applicable restoration period.
Early decisions can affect every part of the claim. Before authorizing demolition, broad cleaning, or disposal of damaged property, owners should understand the policy’s inspection requirements and preserve evidence. These steps after a commercial property fire can help protect both the site and the insurance claim.
Immediate Steps and Evidence Checklist for a Texas Commercial Fire Claim
Safety comes first. Do not enter a fire-damaged structure until the appropriate authorities have cleared it. Once the property is safe, notify the insurer promptly and begin a claim file that separates physical damage, business income, extra expense, and communications. Policy duties and applicable deadlines depend on the policy, governing law, and the facts.
A concise evidence checklist should include:
- Preserve the scene: Photograph and record each affected area, including structural components, smoke and soot, water or suppression damage, equipment, inventory, and areas that may require further inspection. Retain damaged property when safe and reasonably practical, and document anything that must be moved or discarded for safety.
- Gather the policy and claim file: Keep the declarations, endorsements, exclusions, sublimits, duties after loss, claim number, notices, estimates, reports, and every insurer communication together.
- Track mitigation and repairs: Save invoices, work authorizations, drying or cleaning records, temporary protection costs, contractor estimates, permits, schedules, and progress records. Note what each expense was intended to address.
- Build the business-impact record: Preserve financial statements, tax records, sales data, payroll records, contracts, rent records, inventory data, and records of continuing, avoided, and additional expenses.
- Create a dated timeline: Record the fire, notice, inspections, document requests, emergency work, repair milestones, operating changes, and reopening steps. Keep the related photograph, report, invoice, or communication with each entry.
- Preserve originals and submissions: Keep original electronic files and copies of everything sent to the insurer. If the insurer says information is missing, request a specific list and answer it with a dated supplement.
This checklist is a starting point, not a statement that every item is covered or that one form applies to every policy. For a more detailed commercial fire proof framework, see Hoch Law Firm’s commercial fire damage insurance claim proof for Texas property owners.
How Commercial Fire Losses Become Undervalued
An insurer’s first estimate is not necessarily the measure of the covered loss. It may rely on a brief inspection, incomplete testing, generalized pricing, or assumptions that do not reflect the building’s actual materials and operating requirements. A careful claim evaluation tests those assumptions against physical evidence, policy language, expert findings, and reliable financial records.
| Issue | Why It Matters | Evidence to Preserve |
|---|---|---|
| Hidden structural damage | Heat may impair components that appear intact | Engineering inspections, photographs, testing, repair scopes |
| Smoke and soot | Contamination may spread beyond burned areas | Sampling, HVAC reports, cleaning trials, inventory records |
| Water intrusion | Suppression water may cause concealed moisture damage | Moisture maps, remediation logs, photographs, invoices |
| Code requirements | Current requirements can increase rebuilding cost | Code analysis, permits, contractor estimates, policy endorsements |
| Business interruption | Lost income may continue while operations recover | Tax returns, sales history, contracts, payroll, forecasts |
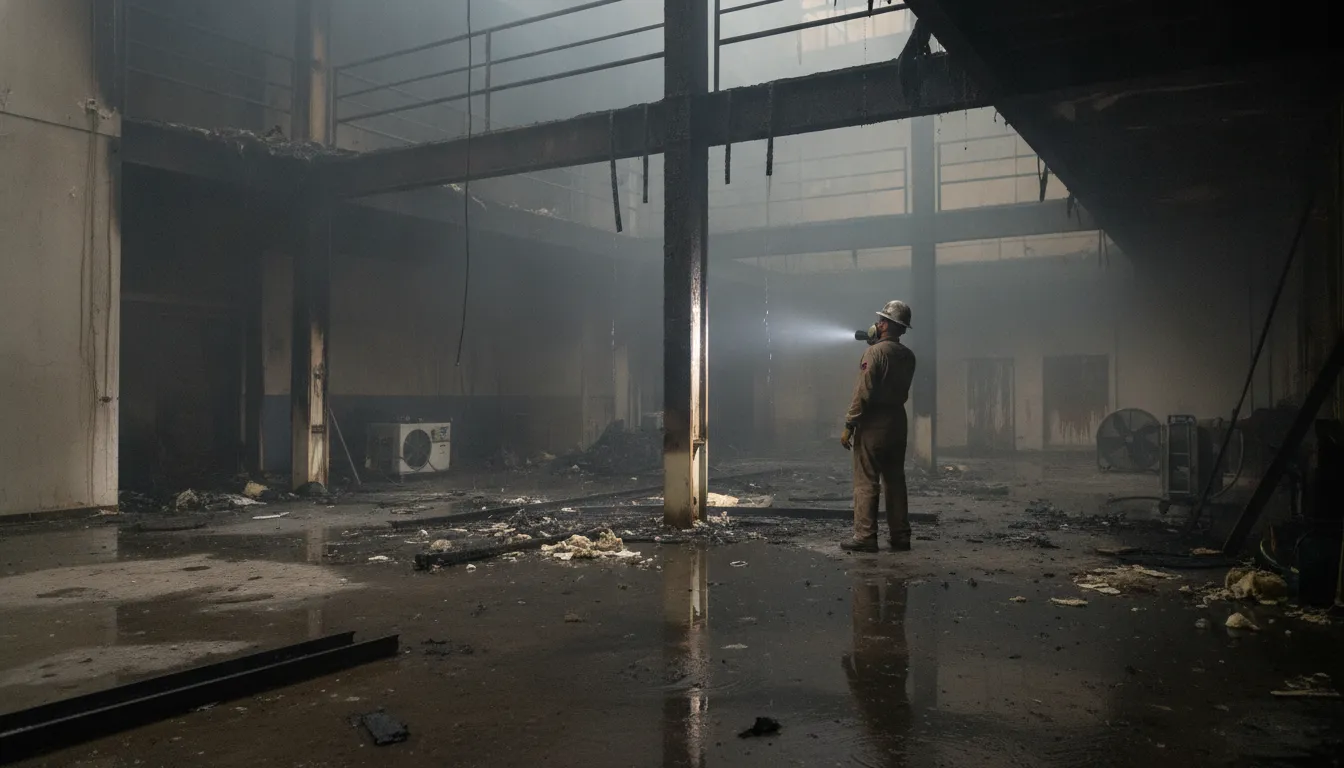
A thorough inspection helps distinguish visible damage from concealed conditions that may affect the repair scope, operating timeline, and value of the claim.
Cleaning Versus Replacement
One recurring dispute is whether damaged material can be cleaned or must be replaced. The correct answer depends on the material, contaminant, intended use, safety considerations, and whether cleaning can restore the property to the condition required by the policy. A superficial cleaning proposal may not address soot within ductwork, persistent odor in porous finishes, corrosion in electronics, or contamination of inventory intended for sale.
Repair Scope and Pricing
Commercial reconstruction may require specialized labor, matching materials, phased work, and coordination with tenants or ongoing operations. Estimates that omit those realities can leave a substantial funding gap. The insurer may also disagree about whether a component was damaged by the fire, whether a proposed repair is necessary, or whether replacement is more economical. Independent contractors, engineers, hygienists, accountants, and other qualified professionals can help define the loss.
Cause and Exclusion Disputes
Insurers investigate the cause of major fires and may examine maintenance, electrical conditions, security, prior claims, and the business’s finances. An investigation does not establish wrongdoing. If an insurer raises an exclusion or suggests intentional conduct, the owner should obtain counsel before providing extensive statements or signing authorizations. A lawyer can evaluate the insurer’s position, preserve favorable evidence, and require the company to identify the policy language and facts on which it relies.
Learn how legal counsel can address a disputed or undervalued property insurance claim.
Business Interruption and Extra Expense After a Commercial Fire
A commercial fire can affect revenue even after emergency work begins. A business-interruption analysis should connect four points: the covered physical loss, the change in operations, the financial effect, and the reasonable restoration period. The policy controls which losses and expenses may qualify, so a decline in revenue alone does not establish the amount of a covered claim.
What the records need to show
Preserve records that show the business before the fire, during the interruption, and as operations resume. Depending on the business and policy, useful records may include monthly financial statements, tax returns, sales reports, contracts, rent records, payroll, inventory data, customer orders, repair schedules, permits, and communications about closure or reduced operations. Separate continuing expenses from avoided expenses. Tie the financial records to the physical damage and the dates when operations changed.
Documenting extra expenses and the restoration period
Keep invoices and explanations for temporary space, equipment leasing, expedited shipping, data recovery, security, relocation, advertising, and other costs incurred to continue operations or reduce the interruption. Also preserve permits, contractor schedules, material-availability records, inspection approvals, and reopening records that explain the restoration timeline. The policy and its endorsements determine whether a specific expense or period is covered.
For a broader documentation framework, see Hoch Law Firm’s business interruption claim documentation for Texas property owners. For service information, see the business interruption claims page. If the insurer disputes the physical loss or the financial calculation, a lawyer can help evaluate the policy, organize the record, and address the disagreement.
Common Disputes With Commercial Property Insurers
A disagreement may begin with a low estimate, a reservation-of-rights letter, repeated document requests, or a partial payment that addresses only the least disputed portion of the loss. Business owners should not assume that continued cooperation requires accepting an incomplete adjustment. The policyholder can comply with legitimate duties while challenging unsupported positions.
- Coverage denial: The insurer asserts that an exclusion applies or that the loss falls outside the policy period or covered property.
- Underpayment: The insurer recognizes coverage but disputes quantities, methods, labor rates, replacement needs, or the value of damaged property.
- Delay: The investigation continues without a clear explanation, meaningful progress, or a decision based on the available evidence.
- Business income disagreement: The parties dispute projected revenue, saved expenses, causation, or the length of the restoration period.
- Compliance allegations: The insurer claims the owner failed to provide notice, protect the property, submit required documentation, or satisfy another policy condition.
A lawyer can examine whether the insurer’s requests are grounded in the policy, organize a response, and develop the evidence necessary to challenge a denial or inadequate valuation. Hoch Law Firm’s work in property insurance claim disputes focuses on protecting the rights of policyholders rather than serving insurers.
What a Fire Damage Insurance Claim Lawyer Does
Effective representation begins with understanding the business, the property, and the policy. Counsel can identify coverage issues, coordinate evidence preservation, evaluate the insurer’s investigation, and help assemble a complete claim. When specialists are needed, counsel can work with appropriate professionals to address engineering, remediation, construction, accounting, or cause-and-origin questions.
A lawyer can also manage formal communications with the insurer, prepare the policyholder for requested examinations or statements, respond to coverage defenses, and document unreasonable delays. If negotiation does not produce an appropriate result, counsel can evaluate litigation and present the claim in court. Trial readiness matters because the strength of the evidence and the ability to prove the case can influence the insurer’s willingness to resolve a dispute fairly.
Cost should not prevent a business from seeking help after a severe loss. Hoch Law Firm offers contingent-fee representation for commercial fire claims. The firm provides direct attorney access and personalized guidance so the owner understands the strategy, the evidence being developed, and the next step in the matter.
When to Contact Counsel
Business owners benefit from legal advice before evidence disappears or a disputed position hardens. Counsel should be considered promptly when the insurer issues a denial, offers substantially less than documented repair costs, disputes widespread smoke damage, questions the cause of the fire, demands an examination under oath, delays a coverage decision, or challenges business income calculations.
Early consultation can also help when no dispute has been formally declared. Major commercial losses involve technical evidence and policy requirements that are difficult to recreate later. A lawyer can help the business avoid premature disposal of evidence, incomplete submissions, inaccurate recorded statements, and releases that may end the claim before all damage is known. Owners can review further information about working with a contingency lawyer after a commercial fire before deciding how to proceed.
Call Hoch Law Firm at 817-731-9703 to discuss a disputed Texas commercial fire claim.
Frequently Asked Questions
What should I do before cleaning a fire-damaged commercial property?
Confirm that the property is safe, notify the insurer, photograph and record all affected areas, and preserve damaged items when practical. Before broad cleaning or demolition begins, determine whether the insurer and necessary experts have had an opportunity to inspect. Document any emergency work required to prevent additional damage.
Can a commercial fire claim include smoke and water damage?
It may, depending on the policy and facts. Smoke, soot, suppression water, and chemicals can damage areas and property that flames never touched. Testing, photographs, remediation records, and expert assessments can help establish the extent of the covered loss.
How is business interruption loss calculated after a fire?
The calculation generally compares the business’s expected financial performance without the fire to its actual performance during the covered interruption, subject to the policy. Historical financials, contracts, sales trends, saved costs, and reasonable forecasts may all be relevant. The applicable restoration period and extra expenses must also be evaluated.
When should a Texas business hire a fire damage insurance claim lawyer?
A business should consider counsel when the loss is substantial, evidence is technically complex, the insurer delays its decision, or a dispute develops over cause, coverage, repair scope, value, or business income. Consulting counsel early can help preserve evidence and prevent avoidable claim errors.
How does Hoch Law Firm charge for commercial fire claim representation?
Hoch Law Firm offers contingent-fee representation, meaning the fee is tied to the recovery under the representation agreement. The firm offers a free case evaluation so a business owner can discuss the claim and potential next steps before deciding whether to proceed.
Protect the Value of Your Commercial Fire Claim
A serious fire creates immediate operational pressure, but the decisions made during the claim can affect the business long after repairs are complete. Preserve the site, gather the full policy, document every category of loss, and obtain advice before accepting a final valuation or signing a release. Hoch Law Firm exclusively represents policyholders and injured parties and provides personalized, direct attorney access throughout the matter.
Call Hoch Law Firm at 817-731-9703 for a free case evaluation of your Texas commercial fire claim.