When an insurer delays a property claim, owners need more than a promise that the file remains under review. Texas prompt payment claim delay options for Texas property owners begin with identifying deadlines, preserving proof of submissions, and comparing each response with the policy and Texas law.
Call Hoch Law Firm at 817-731-9703 for a claim evaluation.
Texas Insurance Code Chapter 542 generally requires an insurer to acknowledge a first-party claim and begin investigating. The insurer must request reasonably required materials, decide whether to accept or reject the claim, and pay after acceptance within defined periods. The exact analysis depends on the policy, insurer, claim facts, proof-of-loss materials, and applicable exceptions.
The first step is understanding what the prompt-payment rules require and what an owner can do when a carrier does not act on time.
What Texas Property Owners Should Know About Texas Prompt Payment Claim Delay Options
A first-party property claim is a claim the insurer pays directly to the insured or beneficiary. That differs from a liability claim, where the policyholder may be seeking coverage for an allegation made by someone else. For a Texas commercial property owner, a first-party claim may involve building damage, equipment, inventory, lost rents, business interruption, or other covered losses, depending on the policy.
Texas Insurance Code Chapter 542 applies generally to insurers authorized to conduct insurance business in Texas. The statute is intended to promote prompt payment of insurance claims. It establishes timing requirements for acknowledging a claim, beginning an investigation, requesting reasonably required materials, deciding whether to accept or reject the claim, and issuing payment after acceptance. The statutory text is available through the Texas Legislature.
Those requirements do not mean every claim that remains open is automatically unlawful. The insurer may need to inspect the property, evaluate causation, interpret exclusions or endorsements, or assess whether the claimed damage falls within the policy. The policyholder also may need to provide a proof of loss, records, invoices, photographs, expert reports, or other information reasonably required to evaluate the claim. Policy language and the facts of the loss determine what information is relevant.
The important question is whether the insurer is acting within the applicable statutory periods and communicating a legally sufficient reason when additional time is needed. Chapter 542 generally requires written notice of acceptance or rejection after the insurer receives the materials required for final proof of loss. If the insurer cannot decide within the applicable period, it generally must explain the reason for needing more time. Special rules and exceptions may apply, including for eligible surplus-lines insurers or certain catastrophic events.
Owners evaluating Texas prompt payment claim delay options for Texas property owners should preserve the policy, claim notice, proof-of-loss materials, requests from the insurer, inspection records, status correspondence, and evidence of ongoing financial losses. Keep separate track of Texas property claim deadlines, because prompt-payment obligations and limitations periods are related but distinct issues.
How Texas Property Owners Can Use Texas Prompt Payment Claim Delay Options
- Preserve notice and proof of loss. Keep the original written notice of claim, the date and method of delivery, the policy, photographs, videos, repair estimates, invoices, inspection reports, and any proof-of-loss materials. Texas Insurance Code Chapter 542 generally requires an insurer to acknowledge a claim, begin investigating, and request reasonably required items within 15 days after receiving notice. After receiving the materials required for final proof of loss, the insurer generally must accept or reject the claim in writing within 15 business days, subject to policy, insurer, and statutory exceptions. A clear record helps establish what the carrier received and when. Keep a separate calendar for Texas property claim deadlines, because prompt-payment deadlines do not replace other time limits.
- Request a written status and decision. Send a focused written request identifying the claim number, date of loss, documents already provided, outstanding requests, and the specific decision or explanation you need. Ask the insurer to identify any missing information, the reason additional time is required, and the expected date for its coverage and payment position. Save the request and the response. Chapter 542 generally requires an insurer that cannot decide within the applicable period to provide reasons for needing more time. A vague statement that the claim is still under review may not answer whether required deadlines were met.
- Organize communications, costs, and continuing losses. Maintain a timeline of calls, emails, inspections, requests, partial payments, and promised follow-ups. Record emergency repairs, mitigation expenses, financing costs, lost rents, business interruption, extra expense, payroll, and other losses that may relate to the covered event. Preserve documents showing the condition before and after the loss. Do not assume every expense is covered, but do not discard evidence before the policy and causation issues are evaluated. If the property is commercial, keep current financial records while the claim remains open.
- Assess the response against the policy and facts. Compare the insurer’s written position with the policy’s coverage grants, exclusions, conditions, valuation provisions, deductibles, and endorsements. Determine whether the dispute concerns coverage, causation, the amount of damage, missing proof, or the timing of payment. An insurer’s delay is not automatically unlawful, and statutory deadlines can have exceptions. Conversely, a claim being pending for further review does not by itself resolve whether the carrier acted within applicable deadlines. The Texas Department of Insurance has stated that carriers must meet applicable prompt-payment timeframes even when claims are pended for further review.
- Choose an escalation path based on the dispute. If the disagreement is primarily about the amount of covered damage, review whether the policy permits appraisal. Appraisal is generally valuation-focused and may not decide coverage, causation, statutory delay, or every other legal issue. Read Hoch’s guide to appraisal versus litigation before treating appraisal as a complete solution. Depending on the facts, an owner may also submit a complaint to TDI, continue targeted negotiations, or evaluate litigation. Those options involve different procedures, costs, deadlines, and evidentiary requirements. A policyholder-side attorney can review the policy, claim file, timeline, and financial impact before an owner commits to a path.
What Deadlines Does the Texas Prompt Payment of Claims Act Set?
Texas Insurance Code Chapter 542 establishes general timing requirements for many first-party insurance claims. A first-party claim is one paid directly to the insured or beneficiary. The deadlines below are a practical framework, not a substitute for reviewing the policy, claim history, insurer type, and facts of the loss. The statute also contains exceptions that can change how a deadline applies.
General Texas prompt-payment timelines for property claims
| Claim event | General statutory period | Practical owner response |
|---|---|---|
| Notice of claim is received | Generally, within 15 days, the insurer must acknowledge the claim, begin investigating, and request items, statements, or forms it reasonably believes are required. | Keep the written notice, delivery confirmation, claim number, and every document request. Ask the insurer to identify any missing material specifically. |
| Required proof-of-loss materials are received | Generally, within 15 business days after receiving all required items, statements, and forms, the insurer must notify the claimant in writing that it accepts or rejects the claim. | Preserve the proof-of-loss submission and the date the insurer received it. Request a written coverage decision rather than relying on informal status updates. |
| Insurer cannot decide within the applicable period | The insurer generally must give the claimant written reasons it needs additional time within that same applicable period. | Review whether the explanation identifies a genuine unresolved issue. Continue documenting communications, inspections, estimates, expert reports, and financial effects of the delay. |
| Insurer gives notice that it will pay all or part of the claim | Generally, payment is due within five business days after the payment notice. If payment depends on an act by the claimant, the period generally runs after that act is completed. | Confirm the amount, payment conditions, and required claimant action in writing. Record when each condition was completed and when payment was actually received. |
These are general periods under Texas Insurance Code Chapter 542. Eligible surplus-lines insurers can have different periods, including longer initial-response and payment periods. Other statutory exceptions or a catastrophic-event extension may also affect the calculation. A missed date does not automatically resolve coverage, liability, or damages. But it can be important evidence when evaluating Texas prompt payment claim delay options for Texas property owners.
What Can You Do When an Insurer Says It Needs More Time?
Start by asking what remains under investigation, what information the insurer still needs, and when you can expect a written coverage decision. A documented investigation is different from silence. An insurer may need photographs, estimates, engineering analysis, sworn proof of loss, or other reasonably required materials. But a general statement that the claim is “still under review” does not answer whether the carrier is meeting its statutory obligations.
Under Texas Insurance Code Chapter 542, an insurer generally must notify the claimant in writing of acceptance or rejection within 15 business days after receiving the items required to establish final proof of loss. If it cannot decide within that period, it must notify the claimant of the reasons it needs additional time within the applicable response period. The controlling deadline can vary by policy, insurer type, claim facts, and statutory exception. Review the insurer’s letter against the claim timeline, rather than assuming that a delay is automatically unlawful.
Keep the claim record organized. Preserve the notice of loss, policy, proof-of-loss materials, document requests, inspection reports, estimates, status emails, payment notices, and evidence of continuing expenses. Send a written status request that identifies unanswered questions and asks the insurer to confirm the next decision date. Texas law also identifies failures to promptly acknowledge pertinent claim communications and to use reasonable standards for prompt investigation as unfair claim settlement practices. Read Chapter 542 for the statutory text.
Your next option depends on the dispute. Appraisal may help resolve a disagreement about the amount of covered loss, but it generally does not decide every coverage, causation, or delay issue. Review the policy before invoking it. Hoch’s guide to appraisal versus litigation explains that distinction.
A complaint to the Texas Department of Insurance, continued negotiation, or litigation may also be appropriate, depending on the evidence and policy language. None guarantees payment or a particular result. If the insurer remains unresponsive, offers an unexplained delay, or disputes a substantial loss, a policyholder attorney can evaluate the record, deadlines, and available remedies.
How a Delayed Claim Can Affect Texas Businesses and Property Owners
A delayed property claim can create financial pressure long before the insurer issues a final decision. A damaged building may need emergency work, temporary protection, or full repairs. If payment does not arrive, an owner may have to decide which work can proceed, which vendors can be paid, and how to protect the property from further damage while preserving the claim.
For a business, the loss may extend beyond the physical structure. Depending on the policy language and the facts, the claim may involve business interruption, extra expense, payroll during a closure, loss of rents, utility-service interruption, or tenant displacement. A delay can disrupt cash flow, interfere with lease obligations, and increase pressure from a lender or other financing party. Coverage is not automatic, so each category must be evaluated against the policy, the cause of loss, and the available proof.
Call Hoch Law Firm at 817-731-9703 to discuss a delayed Texas property claim.
Track the financial effects as they develop
Keep a separate record of repair estimates, invoices, photographs, inspection reports, mitigation expenses, payroll records, rent rolls, leases, vacancy information, and correspondence with the insurer. Preserve financial statements and other records that show the property’s operation before and after the loss. Do not assume that a later payment will account for losses that were never documented.
Owners should also record temporary measures, added operating costs, cancelled or delayed projects, tenant communications, and lender notices. Clear records help connect the property damage to the claimed financial impact and give counsel a more reliable basis for evaluating coverage, valuation, and delay issues. Hoch’s guide to claim documentation for property owners provides a focused starting point.
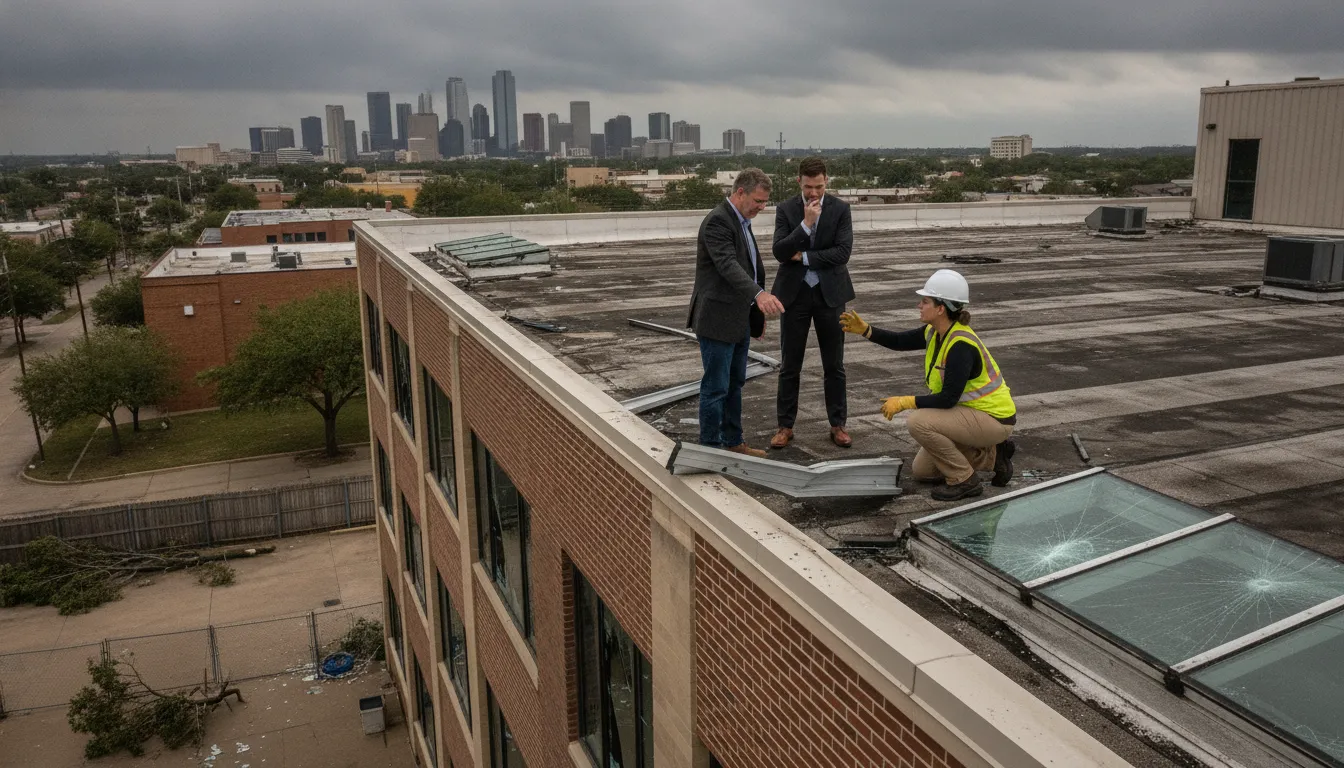
For commercial owners, a commercial property insurance review can help identify the coverages and exclusions that may control the dispute. If the delay is affecting repairs, operations, tenants, or financing, an evaluation of the commercial property claim dispute may clarify the next practical step.
When Should You Contact a Lawyer About Texas Prompt Payment Claim Delay Options?
Flood damage is one example of a disputed property-loss cause, but the same prompt-payment and documentation questions can arise after storms, fires, water losses, or other covered events. Consider a legal review when the claim stops moving, the carrier’s position does not match the policy, or financial consequences continue to grow. A delayed response may affect repairs, tenants, rents, cash flow, business operations, and lender relationships. You do not need to wait for a final denial before asking whether the claim is being evaluated under the right coverage provisions.
One practical trigger is a disputed source of water or an unclear coverage position. Review the policy and written communications if the insurer characterizes the loss as flood damage without addressing other possible causes, relies on an exclusion without explaining its application, or requests repeated documentation without identifying what remains missing. Also seek review before signing a release or submitting a disputed proof of loss.
An evaluation is useful when the carrier underpays building damage, omits contents or machinery, disputes the water source, or treats a business-income loss as unrelated. Commercial coverage may involve building property, inventory, fixtures, business interruption, extra expense, payroll, loss of rents, or utility interruption. Each category depends on the policy and facts. Keep the policy, declarations, endorsements, photographs, videos, mitigation records, estimates, invoices, expert reports, business-loss records, and correspondence together. For related financial records, review business interruption claim documentation.
Hoch Law Firm represents policyholders in the Dallas-Fort Worth and North Texas markets, not insurance companies. A review can include policy interpretation, causation analysis, comparison of pre-loss and post-loss conditions, expert damage assessment, and an evaluation of negotiation or litigation options. Learn more about commercial property insurance claims. A consultation evaluates the claim. It does not guarantee coverage, representation, or recovery.
Frequently Asked Questions
Does commercial property insurance cover flood damage?
Coverage depends on the policy’s definitions, exclusions, endorsements, deductibles, limits, and conditions. Flood insurance may require a separate policy, while water entering through a storm-damaged roof or broken window may present a different coverage question. Review the actual policy and evidence before assuming that a loss is covered or excluded.
What evidence helps prove the cause of water damage?
Preserve photographs, videos, waterline and debris observations, weather information, drainage conditions, roof or building inspections, maintenance records, mitigation invoices, and witness accounts. Keep the original files and a dated timeline. The useful evidence depends on the disputed source, pathway, timing, and extent of the loss.
What if water entered through a storm-damaged roof?
Water entering through a storm-created opening may raise a different policy question from rising surface water, but no general rule decides coverage. The policy language, causation evidence, exclusions, endorsements, and facts must be analyzed together. Avoid repairing away important evidence before it can be documented safely.
Can business interruption be part of a delayed property claim?
Possibly, if the policy provides business-income, extra-expense, loss-of-rents, payroll, or related coverage and the loss satisfies its terms. Track closures, reduced operations, continuing expenses, tenant effects, lost rents, and other financial impacts. Coverage and any recovery depend on the policy and supporting proof.
When should a lawyer review a delayed property claim?
Consider a review when the carrier disputes the source of water, relies on an exclusion, denies or underpays the claim, requests repeated records without clarity, or the loss is affecting repairs, tenants, cash flow, or lenders. Counsel can evaluate the policy, evidence, expert needs, and available recovery options without assuming a particular result.
Talk With Hoch Law Firm About Texas Prompt Payment Claim Delay Options
A delayed property claim can turn on policy language, causation evidence, exclusions, statutory deadlines, and the financial effect on the owner or business. A fact-specific review may help clarify the issues affecting your claim and the options available under the policy.