A disagreement with an insurer often begins with a few words in the policy: a definition, exclusion, condition, or limitation that each side reads differently. For a Texas property owner, that reading can affect repairs, business interruption, tenant obligations, and cash flow before anyone agrees on what the loss is worth.
Call Hoch Law Firm at 817-731-9703 to discuss your property insurance dispute.
A property insurance policy interpretation dispute for Texas property owners is a disagreement about what the policy requires, permits, or excludes. Because the policy is a contract with the insurer, the relevant wording and the facts of the loss both matter. Texas Department of Insurance guidance explains that disputes can arise when the policyholder and insurer read the policy differently: TDI claim guidance.
The practical starting point is to identify the language driving the disagreement, preserve the claim record, and separate coverage questions from the amount of damage. The sections below explain how those issues can shape the next decision for a Texas property owner.
What Is a Property Insurance Policy Interpretation Dispute for Texas Property Owners?
A property insurance policy interpretation dispute for Texas property owners concerns what the policy means and how its provisions apply to a claimed loss. A policy is a contract between the policyholder and the insurance company, so the relevant analysis starts with the policy text, endorsements, definitions, exclusions, conditions, and limits. A disagreement may arise when the policyholder and insurer read that language differently.
That issue is separate from valuing the damage. Valuation asks how much it will cost to repair or replace covered property, or how a covered financial loss should be measured. Interpretation asks whether the policy provides coverage, what conditions apply, and how a limitation or exclusion operates. The two questions can overlap in a claim, but a detailed repair estimate does not by itself resolve a disagreement about what the contract covers.
Policy language is not ambiguous merely because the parties disagree. Texas Supreme Court authority describes ambiguity as genuine uncertainty that remains after the applicable interpretation rules are applied to the face of the policy. In RSUI Indemnity Co. v. The Lynd Co., 466 S.W.3d 113 (Tex. 2015), the Court held that competing reasonable constructions of a commercial property policy made the language ambiguous and construed the ambiguous language in favor of coverage. Read the official Texas Supreme Court opinion for the decision. Those principles depend on the wording and facts of the particular dispute, and they do not create an automatic coverage conclusion.
For a commercial owner, the practical stakes can extend beyond the building itself. Depending on the policy, interpretation questions may affect inventory, equipment, business interruption, rents, or extra expenses. Commercial property insurance guidance can help frame those issues, but the policy and claim record control the analysis.
How Does a Property Insurance Policy Interpretation Dispute for Texas Property Owners Affect Coverage?
A policy-language dispute often turns on how several provisions work together, not on one isolated sentence. Start with the insuring agreement, which describes the property, causes of loss, and types of damage the insurer agrees to cover. Then review the exclusions, which remove or limit coverage for specified risks or conditions. Texas commercial property disputes may involve denial, underpayment, delay, or disagreement about a wear-and-tear exclusion. The exclusion’s wording, its exceptions, and the surrounding provisions all matter.
Conditions create duties for the policyholder and insurer. Depending on the policy, those duties may address notice, proof of loss, cooperation, examinations, repairs, or dispute procedures. A missed condition can become central to a claim disagreement, but its effect depends on the actual contract language and the facts. Limits then determine how much coverage may be available for a covered loss. They may apply to a particular type of property, location, occurrence, or coverage part. Do not assume that a limit has one obvious application without reading the definitions and schedule with it.
Causation is another frequent pressure point. The parties may disagree about whether a covered event caused the damage, whether an excluded condition contributed to it, or whether separate damage occurred at different times. Commercial coverage issues can reach buildings, inventory, machinery, fixtures, business interruption, rents, and other losses, depending on the policy. A coverage analysis should identify the provision tied to each claimed loss rather than treating the entire claim as one undifferentiated amount.
Texas policy interpretation generally requires reading the policy as a whole. The Texas Supreme Court has explained that provisions should be considered together, and that language is ambiguous only when competing reasonable interpretations remain after applying the relevant interpretation rules. The result is not a reader-specific coverage conclusion. Ask the insurer to identify the policy language it used to settle the claim, then compare that explanation with the complete policy. For additional context, review these Texas commercial property exclusions.
What Evidence Should Texas Property Owners Preserve?
Strong documentation can help clarify what happened, when it happened, and how the claimed loss developed. Preserve evidence before repairs change the condition of the property, while also taking reasonable steps to prevent additional damage when the policy or circumstances require it.
- Build a complete claim file. Keep the policy, endorsements, notices, estimates, adjuster reports, emails, letters, photographs, videos, invoices, and other claim documents together. For calls with the insurer, record the date, subject, name, and title of the person you spoke with. The Texas Department of Insurance recommends keeping copies of claim documents and notes about insurance-company calls. Texas Department of Insurance claim guidance provides the agency’s general recommendations.
- Confirm important conversations in writing. After a call, send a concise email or letter summarizing what was discussed and identifying any requested documents or next steps. This creates a clearer record than relying on memory, especially when several people are involved in a commercial claim.
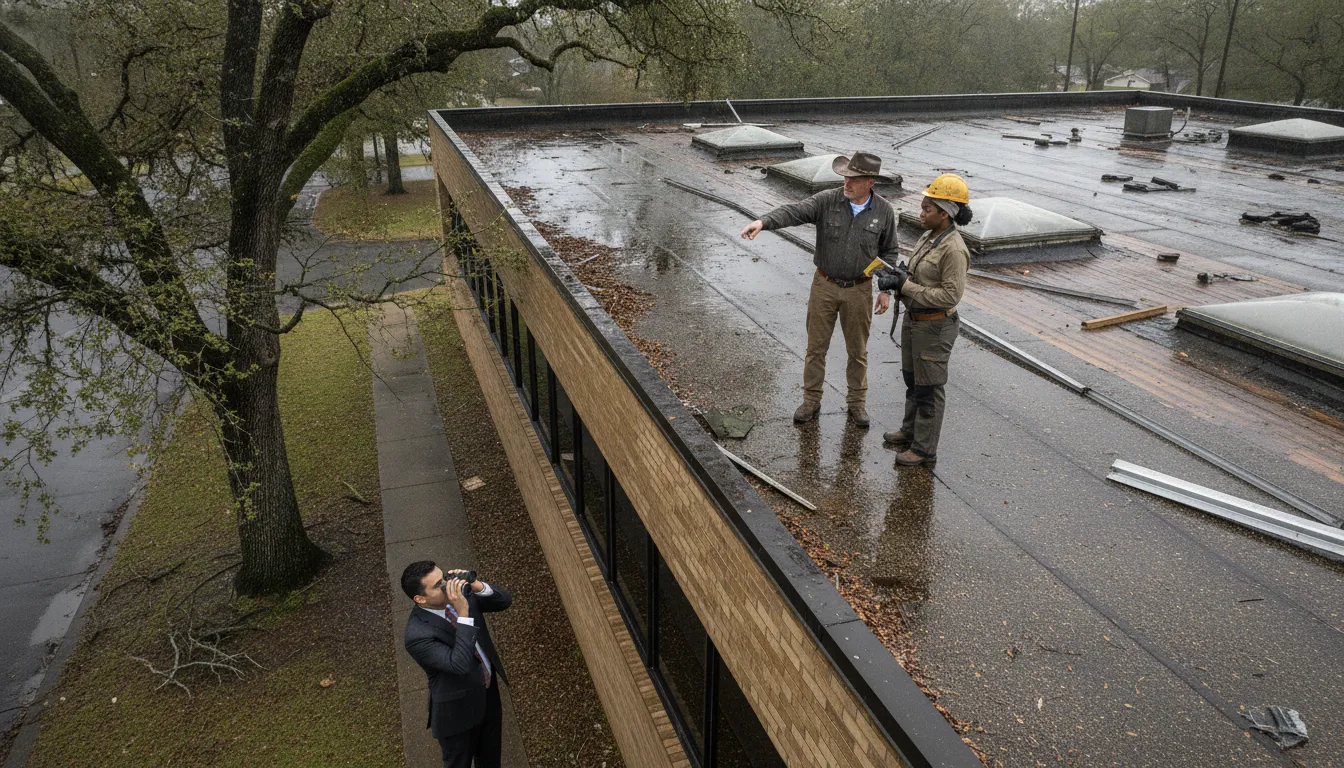
- Record the condition before repairs when possible. Take dated photographs and videos from multiple angles. Capture exterior areas, interior spaces, equipment, inventory, finishes, and any areas that show the path or extent of damage. Keep original files and note when and where each image was taken. If emergency work is necessary, document the condition first when reasonably possible.
- Preserve repair and loss documentation. Keep receipts for repairs and copies of contractor estimates, scopes of work, invoices, engineer or consultant materials, and proof of completed work. If a business operation, tenants, inventory, or rents are affected, preserve related records that may help explain the claimed loss. Send supporting materials through a traceable channel and keep what you submitted.
Evidence does not determine coverage by itself. The policy wording, the facts, and the applicable Texas law control how a dispute is evaluated, so avoid discarding damaged materials or signing a final release before understanding the consequences.
When Can Appraisal Help, and What Does It Decide?
Appraisal can be useful when the central disagreement concerns the amount of a covered loss, but it is not a universal solution for every property insurance policy interpretation dispute for Texas property owners. The policy controls whether appraisal is available, what procedure applies, and what issues the appraisers may decide. Texas Department of Insurance guidance says a policy may include an appraisal process for resolving a dispute, so the appraisal clause should be reviewed before making a demand.
Under the process TDI describes, the policyholder and insurer each select an appraiser. Those appraisers prepare their own estimates of the loss. If they disagree, they select a third person to act as umpire. The umpire makes the final decision described by the process, and that decision binds both sides. This can help resolve competing repair or damage estimates, but it does not automatically decide whether the policy covers the loss in the first place.
| Dispute path | Primary question | Key limitation |
|---|---|---|
| Policy interpretation | What do the policy’s insuring agreements, exclusions, conditions, and limits mean when read together? | It requires close analysis of the policy wording and facts. A disagreement is not automatically an ambiguity or a covered claim. |
| Appraisal | What is the amount of the covered physical loss under the applicable appraisal process? | It may address valuation, but generally does not resolve every coverage, causation, legal, or policy-interpretation issue. |
| Mediation | Can a neutral third party help the policyholder and insurer reach a negotiated resolution? | Mediation is a settlement process. It does not guarantee agreement or create a ruling on the merits. |
| Litigation | What legal rights, coverage obligations, damages, or other disputed issues should a court decide? | Court proceedings can be slower and more involved, and the outcome depends on the evidence, policy, pleadings, and governing law. |
Before demanding appraisal, check the policy for deadlines and procedural requirements. TDI also explains that the policyholder generally pays the appraiser they hire and half of the umpire’s expenses under the described process. Those practical obligations matter when evaluating the appropriate next step.
Appraisal may therefore be one part of a broader claim strategy, not a substitute for coverage analysis. A lawyer may need to separate the amount-of-loss question from disputes about exclusions, causation, conditions, or the insurer’s interpretation of the contract. The specific policy language and facts control. Review TDI’s appraisal and claim-dispute guidance for the described process and confirm the policy requirements before acting.
What Texas Claim Timelines and Dispute Options May Apply?
Texas Insurance Code Chapter 542 contains prompt-payment rules for insurance claims. The statute is intended to promote prompt payment, but the applicable deadline can depend on the type of insurer, the information submitted, the claim’s status, and other statutory conditions or exceptions. Review the current statutory text at the Texas Insurance Code Chapter 542 before treating any timeline as applicable to a particular claim.
Under the general rule described in Section 542.055, an insurer generally must acknowledge receipt of a claim and begin investigating by the 15th day after receiving notice. An eligible surplus lines insurer may have a 30-business-day period instead. Section 542.056 generally addresses the written acceptance or rejection of a claim after the insurer receives the items, statements, and forms it requires for final proof of loss. That section also allows additional time in some circumstances, provided the insurer explains the need and follows the statute’s further timing requirements.
For an accepted claim or accepted part of a claim, Section 542.057 generally addresses payment within five business days after notice. Section 542.058 includes a general 60-day provision for certain payment delays when another applicable statute does not specify a period. These provisions do not create a universal countdown for every dispute. Questions about notice, proof of loss, additional information requests, policy conditions, and statutory exceptions can materially affect the analysis. A deadline also may arise from the policy or another law.
If an insurer has denied a claim, paid less than the policyholder believes the policy supports, or delayed its response, Texas Department of Insurance identifies several possible paths. A policyholder may file a complaint with TDI, ask for mediation or another form of alternative dispute resolution, or pursue litigation when appropriate. These options have different purposes and may involve separate deadlines. A policyholder considering how to challenge a denied property claim should preserve the denial, policy language, correspondence, estimates, and supporting records. Those considering how to appeal an underpaid property claim should likewise avoid assuming that an informal discussion extends a contractual or statutory deadline.
Call Hoch Law Firm at 817-731-9703 to discuss a Texas property insurance dispute.
Because deadlines and available remedies turn on the policy, claim history, and governing law, this overview is general information rather than individualized legal advice. The next section addresses circumstances in which consulting a Texas property insurance lawyer may help clarify the available options.
When Should You Consult a Texas Property Insurance Lawyer?
Consider consulting counsel when the insurer’s position depends on a disputed exclusion, a narrow reading of the policy, or an interpretation that does not account for the full loss. A denial, substantial underpayment, or unexplained delay can also justify an informed review, particularly when repairs, tenant issues, business interruption, or cash flow are at stake.
Commercial losses may require more than comparing an estimate with a settlement offer. A single claim can involve building damage, inventory, machinery, fixtures, loss of rents, or business interruption. The significance of each item depends on the policy wording, endorsements, claim facts, and available evidence. Complex losses are often a reason to obtain guidance before making statements or accepting a coverage position.
Complex losses may also require technical or financial evidence. Whether an engineer, accountant, or other expert is appropriate depends on the policy, claimed damage, and disputed issues, and should be evaluated with counsel. The right evidence can help clarify causation, scope, valuation, or business-income questions without assuming that every claim requires the same approach.
Policy language and the facts control every coverage analysis. An attorney can help identify the provisions at issue, organize the claim record, and assess available dispute options based on the particular circumstances. For additional context, review this guide on when to hire a property insurance lawyer.
Frequently Asked Questions
What is a Texas insurance appraisal, and when is it used?
A Texas insurance appraisal is a policy process that may help resolve a disagreement about the amount of a covered loss. Whether appraisal is available depends on the policy, so review its appraisal provision and any demand deadline before proceeding. Under the process described by the Texas Department of Insurance, each side selects an appraiser, and the appraisers may select an umpire if they cannot agree. TDI explains the appraisal process.
What does appraisal decide in a property insurance dispute?
Appraisal generally addresses the value or amount of damage, not every question about whether the policy covers the loss. Coverage interpretation, exclusions, causation, policy conditions, and legal remedies may require separate analysis. The policy language and facts control, so an appraisal clause should not be treated as a complete solution to a policy-interpretation dispute.
What evidence matters when challenging an insurance claim decision?
Preserve the policy, claim correspondence, adjuster estimates, photographs or videos taken before repairs when possible, repair receipts, contractor estimates, and records of business or property losses. Keep dated notes of calls, including the person and title, and follow up important conversations in writing. These steps reflect guidance from the Texas Department of Insurance.
What Texas claim laws may apply to a delayed or disputed payment?
Texas Insurance Code Chapter 542 contains prompt-payment provisions, but deadlines, conditions, exceptions, and the type of policy can affect how they apply. The statute generally addresses claim acknowledgment, investigation, written acceptance or rejection, and payment of accepted claims. Do not assume a deadline has run or a remedy is available without reviewing the policy, claim record, and applicable law.
When should a property owner obtain legal guidance?
Consider legal guidance when the insurer relies on a disputed exclusion, denies or underpays the claim, delays a decision, or when a commercial loss involves business interruption, rents, inventory, or other interconnected coverage issues. A lawyer can evaluate the policy language and evidence without assuming that every disagreement produces the same legal result.
Ready to Discuss Your Policy Dispute?
Policy language, claim records, and the facts surrounding a loss can all affect how an insurer’s position should be evaluated. A focused review may help clarify the dispute and identify practical next steps without assuming the outcome.